Can you imagine Big Brother has found another way to peek into our personal lives.But when you are asking someone to finance over $100,000 this is what happens. In the past many items have been excluded from credit histories...But alas someone has a new brain storm.From the lenders point of few it gives a fuller picture of just who you are financially ....and really just what is your true buying power? Granted this is a crazy market and lenders are taking a risk with such incredibly low interest rates. However, often credit issues that dealt with medical bills were not weighted as much as some other payment defaults. Corelogic, the company whose brain child this is typically counts these aspects in it's new report. Do you pay your rent on time? Do you have Child Support and do you pay as promised? Have you ever been evicted.....? Understandably this does not paint a great picture if you are outed on these type of questions.............Most Loans are federally backed like Fannie, Freddie and FHA.....which account for 90% of the loans issued. And this new score will not affect whether you are denied or not ...but it could have a lot to do with Higher or Lower Rates and also Banking Fees associated with your loan.....it is never simple!
Credit where credit is due this blog based on a posting in Inman News which sources the Chicago Tribune that its article was based.
For Realty Information of any type please seehttp://www.greatercrestviewhomes.com/ or http://www.theguthrieteam.com/
7 Tips to Sell Your Home Faster to a Younger Buyer
Friday, October 21, 2011
Monday, September 26, 2011
Lasagna Weed Prevention
Should we order a bottle of Chianti too?
I had heard of this method of choking out weeds before but just stumbled on a Fine Gardening*that gave this rather amusing name to the proceedure. It is similar to using a fabric shield to prevent weeds but if you have moved in the last ten years you probably have card board boxes languishing in your attic and free beats most any other price. Also some authorities seem to think the fabric can be problematic. Plus cardboard is so much more GREEN !
| Removing the mulch to reveal the card board |
| The Cardboard was deteriorating after a month... |
I did a modicum of weeding but by no means got all the yucky stuff out. I then started placing cardboard on the two beds I was working on. Ok I even used a small real estate sign but don’t tell Steve my partner! Then I began to liberally water down the cardboard until I got tired of doing that but probably the more water the better. Then I laid down about 3” of mulch. I used Cyprus but pine straw or anything that is appealing will work. My plan was to wait for several months to let the cardboard decompose. Generally that takes about 6 months. Not going to happen! Have those beds look like that for six months no way! So after about 2 weeks could not stand how it looked and went into phase 2 get those plants in the beds….
| Showing the loosened area around plant....this will be recoverd with mulch! |
I removed the mulch in the areas the plants were going to live and then used a box cutter to make large X’s to pull back the cardboard. Piece of cake the cardboard was pliable and the ground was easy to dig into…..I first made sure to unwind any roots that were knotted in tight circles pulling those out to allow them to grow and smoothed soil around them gently. Final step was to smooth the cardboard around the plant leaving a bit of space and then covered the area with mulch…..
I have since learned in another article that planting immediately is ok too! Whew! So let’s all have a glass of Chianti and watch our garden grow!
| Lorapetulum |
| Juniper |
For any type of Realty Issues please go to http://www.greatercrestviewhomes.com/ or http://www.theguthrieteam.com/
Monday, September 19, 2011
Realtor / Counselor .....NO WAY !
![]() |
| We all need someone we trust to give us advice ..... |
Just read the latest newsletter from FAR (Florida Association of Realtors). My eyes immediately went to an article discussing how this down market had changed Realtor's responsibilities. Probably the general public would be amused to find out the main difference is the amount of counseling this market requires agents to do.
We just returned from a listing presentation very different from the ones we would have given 5 years ago. Back then the emphasis was on service and pricing the house right. Today it is about comforting someone who is upside down in their mortgage but makes too much income to qualify for a short sale. Talk about donut holes…this is a big one! It is more about making the client know he is not the only person in this situation. Trying to convince someone whose pride revolves around keeping the financial agreements they made and choosing options that would be best for their future.
Also, it is about covering yourself legally by making sure that they get proper financial (CPA) and Legal advice (Real Estate Attorney.) We try and keep ourselves as informed as possible about all the aspects a client may be faced with but it is always wise to send a client to the source for the complete story……and make them aware of the complete ramifications of what their actions might bring ( IRS for instance!)
The feel good part of this new role is that you leave that client and you feel so grateful that you are secure enough in your own business that every client you meet you do not feel you just have to get them to list their home and that they have to do it right this moment. Yes it is a good feeling leaving someone knowing while you were there you told then exactly what you felt was the best thing for them to do……….
for further information on Real Estate go to http://www.greatercrestviewhomes.com/ or http://www.theguthrieteam.com/
Friday, September 2, 2011
Dream Makers Grant
And you thought all the housing incentives were gone?
![]() |
| Your Dream Home? |
First time home buyers grants are still out there if you know where to go to look .....
Thank Goodness there is still a program that is for the folks that defend our freedom on a daily basis and have a modest income. In actuality it is a down payment for your first home. This is a grant through the Pentagon Federal Credit Union but you do not have to be a member you can apply to any financial institution.
You're eligible for a Dream Makers grant if:
3. The gross household income, including allowances, that you use to qualify for your mortgage loan is:
A maximum of 80% of your community’s median income based on your family size
This is not a free program you must contribute something …the minimum is $500
Dream Makers will match your contribution 3 to 1 up to a maximum of $5000..............Estimate the size of your mortgage …decide what you can contribute plus the dream makers contribution so that the total contribution you and Dream Makers will be 3% to qualify for your loan. Below is a link that will explain more of this advantageous program. This is something you will want to talk with your lender about . There are many loans where you do not have to put anything down . But remember the more you put down the lower your mortgage payment will be and when you are ready to resell the less you have to get for your home. No Repayment of the loan is recquired if you live in the home for 5 years. Certain restrictions do apply so please go to the link below to find out all the details. Happy House Hunting My Friend!
http://www.pentagonfoundation.org/site/PageServer?pagename=dream_index
For general Real Estate Information, Easy Pathway to Local MLS and all manner of other information please go to www.greatercrestviewhomes.com also www.theguthrieteam.com
Tuesday, August 30, 2011
Gardening is Definitely a Passion!
I am unabashedly a lover of gardens. I prefer to think that I have a lot of discernment in what enhances a garden and what does not…others might interpret this as a bit of snobbery and perhaps it is (I hope not!)….I am not wild about Pink Plastic Flamingoes but have seen them in situations that seemed entirely appropriate……..
.....bird baths, bird houses….preferably the ones that look like churches….adorable little stone or concrete creations of everything from St Francis who is erroneously thought to be patron saint of Gardeners…Actually it is St Fiacre…..He is also know to protect Florist , herbalist , potters and yes cab drivers……..
But I digress I need to stay on topic. One of my unrewarded dreams is to have an adorable little Garden Shed. I love the elaborate ones created for pristine gardens that perfectly enhance the theme of the garden and the home.....Lovely creations that are replicas of the beautiful homes they live with…….
Whimsical attempts that create a smile when seen ……….
or those adorable retreats one could retire to the few weeks we are actually comfortable out side………However at this point something modest to store my tools might just be perfect!
For Real Estate Information please go to www.greatercrestviewhomes.com and www.theguthrieteam.com
Tuesday, August 16, 2011
Exciting News on Insurance Front…
![]() |
| .......But First He Did His Homework At CHOICE |
"This Little Piggy Went to The Market…."
To say there is exciting news concerning Insurance sounds like an oxymoron. …but as bored as I am with insurance this perked me up a bit. The State of Florida has tweaked and redesigned a program that began in 2007 the new acronym is CHOICES. Apparently it is a way to compare cost of insurance from county to county. Do not get the idea that you can go there and put in your data and instantly an insurance quote will appear. I want to repeat emphatically this is not a way to get a quote quickly!
But still it is a good starting point. I usually ask the Title Companies who they are seeing most of the hazard insurance policies being written with…..and that is certainly a valid way to start the process. But CHOICES is more factual than anecdotal in its approach. In each county you have 2 subject homes….
· $150,000 home built prior to 2001
· $300,000 home built in 2005
So for each county you can see these 2 entirely different homes and what typical insurance will cost for each. The idea is that in some counties one company might be the highest yet in a county in a different part of the state it could be one of the lowest. So if you are on a strict budget you could check out the lowest 5 on the list for the county you intend to live in. If you are concerned with the ability of the companies to pay claims you might look to a company closer to the top.
There are all sorts of disclaimers from the state emphasizing that the figures stated do not include deductions say for wind mitigation and it certainly is not an endorsement of any particular company but it is a bench mark to encourage consumers to shop around. Many folks come into the state from other areas and have had a previous relationship with a particular company but the company does not insure in our state but will make an exception …….Please be very careful about that this favor the company is granting you ! Compare coverage with in state carriers and ask the agent for the rating that the company is given by the State Insurance Department. High ranked companies are often financially backed by the state when large scale events occur as in hurricane season……
The Message is Shop around, compare….this home is probably your single largest investment you will ever make ….You will be happy you did!
Check out the website at http://www.floir.com/choices
For more Realty Information go to theguthrieteam.com or for IDX and great listings go to greatercrestviewhomes.com
Tuesday, August 9, 2011
OH ......SO I HAVE TO BUY INSURANCE ?
![]() |
| Boring yes, but you must protect his home! |
It's a ..................Yawn Yawn Yawn !
Ok you finally decided where you are going to live, you made the offer they accepted and now as if you aren't tired enough of making decisions the lender recquires you go out and get this place insured! All you want to do is start buying new furniture……..ARGH!
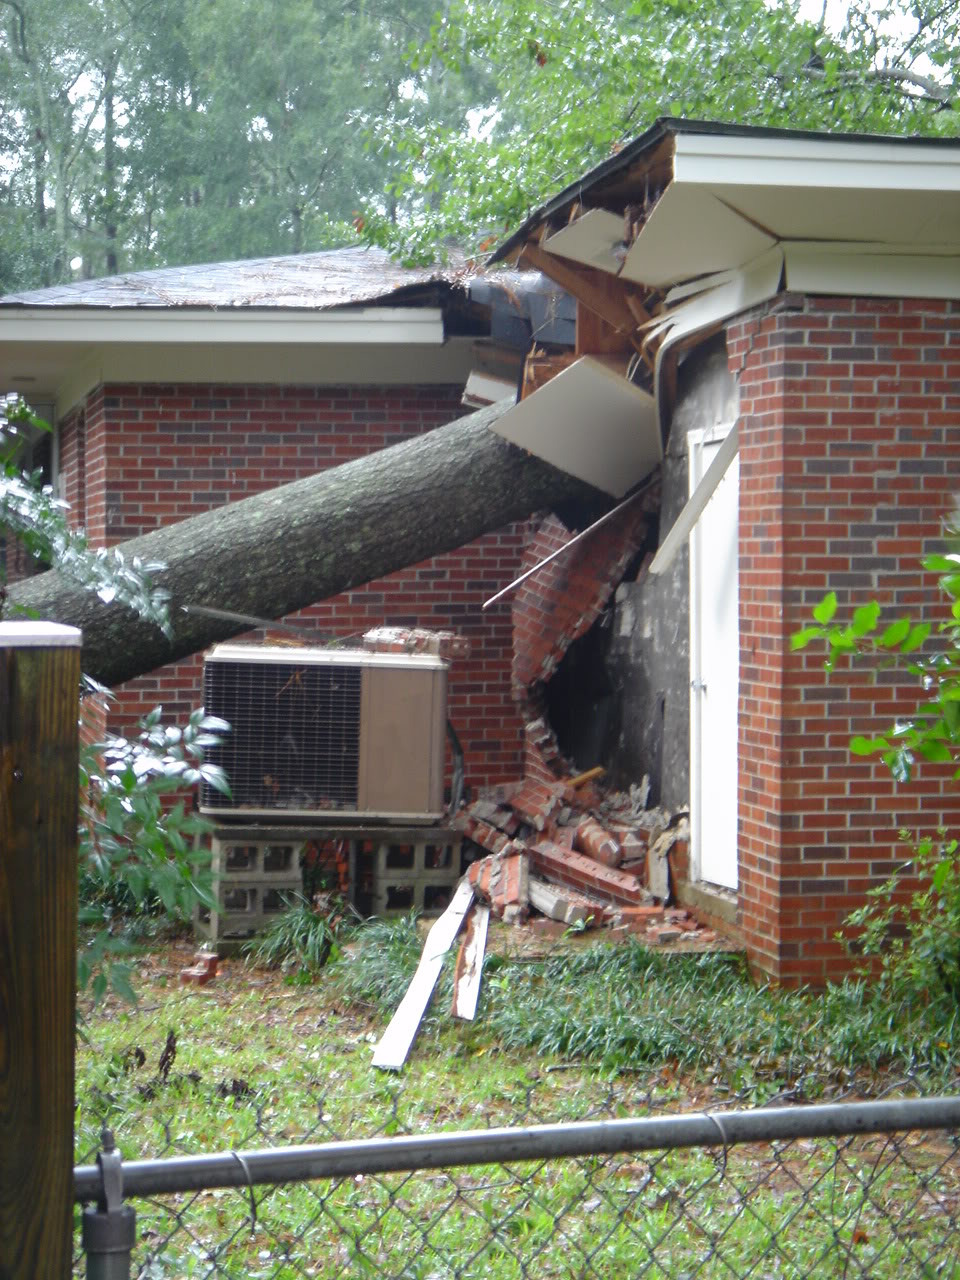
Unfortunately it must be done and the more you know about the subject the more informed you are the better your decisions can be. I have owned our present home since 2002 plus I am a Realtor but some of the following terms were not even on my radar…… Replacement Cost…..Market Value …ALE …Law and Ordinance Coverage…..I know you were about to have a heart attack when I put ALE in the mix….And NO that is not having to take your agent out for a beer……It really is not all that complicated it is just another thing you must educate yourself about if you want to take care of yourself and probably the largest single investment you will ever make…Have I scared you yet? These are terms that will help you understand some of the jargon the insurance agent is going to be throwing at you…….And if he is not you might ask why not?
Replacement Cost or Actual Cash Value: Replacement Cost is the amount of money needed to repair your home without any depreciation for normal wear, tear and usage. Cash Value method is cost to repair your home as well but it takes into account that the roof is 15 years old and its life expectancy is only about 20 years…. So your reimbursement would be for the five years left in the roof……That one is a no brainer……
Market Value vs. Replacement Value: This is particularly hard for the buyer of a brand new home to get their heads around. Most insurance companies want you to carry a replacement value of the home (often 80%)….Market value is what you could sell it for today on the spot……..not how much it would cost to rebuild. The insurance company must factor in such acts of nature like hurricanes or fire ( that is not an act of God, what was I thinking? But you get the idea, right?)…….perhaps at a later date due to inflation or in case of natural disaster materials are scarce and increase rapidly in cost....not to mention labor going up because it is wide spread damamge. If you have a home that would cost $200,000 to replace and you have only $100,000 coverage and you have a partial loss of $50,000 the company may very well award you with $25,000. This is 50 % of the claim which is a formula derived from “amount of insurance needed divided by the amount carried, times the amount of the loss …” All right I don’t like it either but let’s not skimp here for goodness sake.
ALE / Additional Living Expense: When your home is so damaged that you cannot live in it this is what covers that additional expense. Generally it will pay only reasonable excesses above what it would normally cost for you to live. Insurance companies do not normally pay this until a civil authority has pronounced the home not safe for habitation. The other element is that the state does not require that these expenses are paid up-front……so keep good records….Terms and conditions vary from policy to policy so Read carefully. Are you getting the picture you have got to ask lots of questions?
Mold and Fungi: Do not assume your company will include damage from these substances….and when they do you must be aware of the many limits that are placed and in what situations they will actually pay. Some policies will only cover certain perils. The sad part is that flood is not a covered peril on your policy( unless you were wise enought to buy flood insurance .*)So let's say you have a flood and you did not purchase flood insurance the company would not pay for mold as a result of a flood. Good Grief this might take some real thought before you decide what to do......
Law and Ordinance Coverage: This is confusing to say the least. This issue hinges on the perpetual agenda of governments to set standards for construction that offer a minimum level of safety. Do not assume this is a modern approach to the welfare of the public, apparently some 4000 years ago,Hammurabi was tinkering with building codes.The primary difference was if there was a major problem he got the builders head on a platter….that might have some merit today? ( I did not mean that really!!) With our states recent history of hurricanes the building codes have been changing fast and furiously. The problem is that not all homes existing are young enough to have been built to today’s more stringent code. It seems that if only 50 % of the property was damaged but the code says the whole structure must be replaced the insurance company would pay up to the policies limit toward tearing down and rebuilding the undamaged 50%. Insurance companies must include coverage at 25% of the dwelling limit, which as I understand it means the amount you are insured for ( you have to sign a waiver not to have this coverage) In addition to the 25% the insurance companies must offer a limit of 50% above your insured amount….but some will allow you to purchase more. The best advice is to talk to more than one company. Next blog to be about
Comparing Insurance Companies from county to county…there really is an unbiased way….Yawn, Yawn …more about insurance….? I would much prefer to write about designing your home or garden but this is one of those things you must know about!
For More about Real Estate go to http://theguthrieteam.com/ or a more extensive site with IDX /www.greaterpensacolahomes.com
Reference for much of this blog was taken from Jeff Atwater, Chief Financial Officer Fl Dept of Financial Services
* Your Realtor will check to see if you are buying in a zone that is prone to flood ( make sure you ask if the home you are interested is in a flood plain) and your mortgage company will recquire flood insurance if you are .....otherwise it is optional.
Subscribe to:
Posts (Atom)